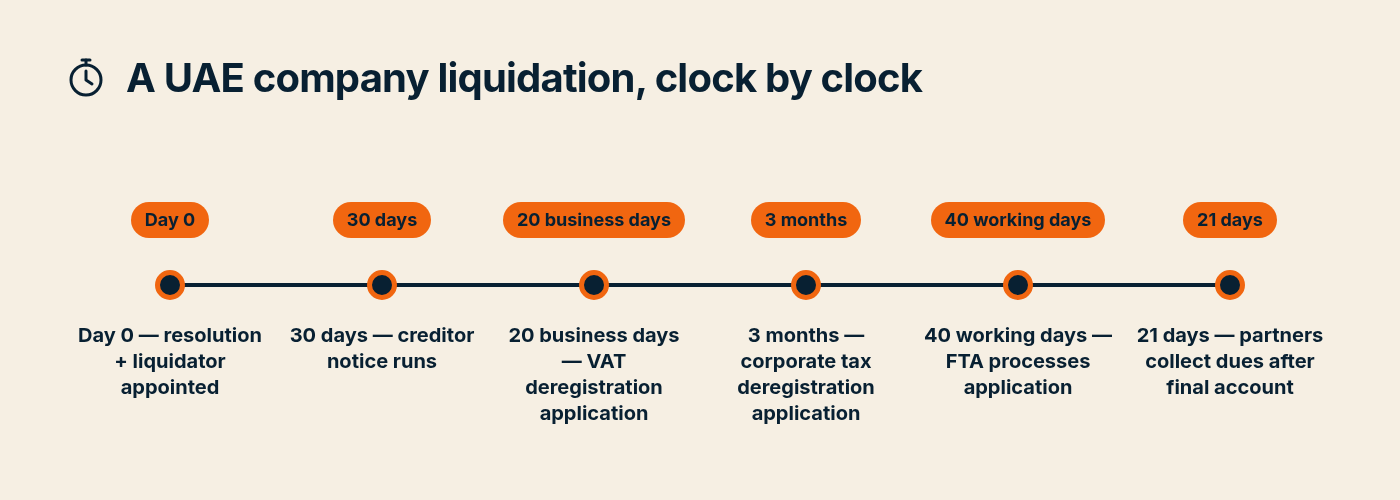
There is no single fixed duration for company liquidation in the UAE, but every stage of the process runs on clocks the law sets in advance. The shortest statutory window is 20 business days — the period a VAT-registered company has to apply for VAT deregistration once it stops making taxable supplies. The longest fixed waiting period is the 30 days creditors get to submit claims after the liquidator publishes the notice of liquidation under Article 324 of Federal Decree-Law No. 32 of 2021. Around those two sit the 3-month corporate tax deregistration deadline and the Federal Tax Authority's 40-working-day processing standard, and together they decide whether a closure finishes in weeks or stretches into a second quarter.
Missing any of these clocks costs money on a company that has already stopped trading: AED 1,000 per month for a late corporate tax deregistration application, capped at AED 10,000, and a scheduled penalty for a late VAT deregistration application. This page maps every deadline in a 2026 UAE closure, mainland and free zone, so licence cancellation, tax deregistration and the final filings are sequenced in the right order. If you would rather have one team run that sequence, Finanshels provides company liquidation services in the UAE, including the VAT and corporate tax deregistration steps covered below.
TL;DR
- A mainland liquidation cannot finish in under about six weeks — the 30-day creditor notice in Article 324 is mandatory.
- File corporate tax deregistration within 3 months of cessation; late costs AED 1,000 per month, capped at AED 10,000.
- VAT deregistration: apply within 20 business days; the FTA replies within 20 business days.
- The FTA takes up to 40 working days to process a corporate tax deregistration application.
- Free zones set their own notice periods — confirm your authority's checklist before starting.
How long does company liquidation take in the UAE?
For a solvent mainland LLC, the licence-cancellation stage alone cannot complete in under roughly six weeks from the shareholders' resolution: appointing the liquidator, notifying creditors and running the 30-day minimum notice take a calendar month before the authority will close the file. The tax side runs in parallel and can outlast the licence — corporate tax deregistration must be applied for within 3 months of cessation, and the FTA then has up to 40 working days to process it. Company closure in the UAE is therefore measured in months, not weeks, even when everything goes right, and every deadline below is one you can start counting on day one.
| Clock | Starts on | The deadline | Source |
|---|---|---|---|
| Creditor claims | Notice of liquidation published | 30 days minimum | Federal Decree-Law 32/2021, Art 324 |
| UBO register handover | Liquidator appointed | 30 days | Cabinet Resolution 109/2023, Art 8(7) |
| VAT deregistration application | Company becomes eligible to deregister | 20 business days | Cabinet Resolution 37/2017 |
| FTA reply on VAT deregistration | Application received | 20 business days | Cabinet Resolution 37/2017 |
| Corporate tax deregistration application | Entity or business ceases / dissolution | 3 months | Federal Decree-Law 47/2022, Art 52 |
| Final CT return and payment | End of the tax period | 9 months | Federal Decree-Law 47/2022, Art 54 |
| FTA processing of CT deregistration | Complete application received | 40 working days | FTA service standard, 2026 |
| Partners collect dues | Final account approved | 21 days maximum | Federal Decree-Law 32/2021, Art 329 |
Clock 1: the 30-day creditor notice (mainland)
Under Federal Decree-Law No. 32 of 2021 on Commercial Companies, all debts payable by the company become immediately outstanding on dissolution. The liquidator must notify every known creditor by registered letter inviting their claims, and the same notice of liquidation goes into two local daily newspapers, one in Arabic. In all cases the notice gives creditors at least 30 days from the date of the notice to present their claims (official text of Federal Decree-Law 32/2021, Article 324). The clock starts on the date stated in the notice, not on the day the newspapers print it — a poorly worded announcement quietly adds days.
While the notice runs, the liquidator settles: debts are paid, disputed claims are parked against a deposit, and the liquidator reports to the partners periodically during the liquidation. Only after the general assembly approves the final account does the wind-up complete. Partners are then notified to collect their dues within no more than 21 days, under an announcement published in the same two newspapers (Article 329). Counted from resolution to approved final account, a mainland liquidation therefore carries a statutory floor of roughly eight weeks even when no creditor raises a claim.
Clock 2: corporate tax deregistration — 3 months, then the meter runs
A UAE company does not stop being a taxable person when it stops trading. Article 52 of Federal Decree-Law No. 47 of 2022 requires the entity to file a tax deregistration application within 3 months of the date it ceases to exist, its business ceases, or it is dissolved or liquidated. Miss the date and the penalty is AED 1,000 for each month of lateness, up to a maximum of AED 10,000, under the corporate tax administrative penalties schedule (Cabinet Decision No. 75 of 2023, official text) — the same schedule behind every other fine listed in the UAE corporate tax penalties table for 2026.
The final corporate tax return follows the ordinary rule rather than the liquidation: filed and paid within 9 months of the end of the relevant tax period (Article 54). A company liquidating in mid-2026 with a December 2025 year-end files its last return by 30 September 2026 no matter when the deregistration application goes in. The two deadlines are independent, and the return deadline usually arrives first.
The FTA's published service standard is to process a corporate tax deregistration application within 40 working days of a complete application, with a further 40-working-day window when additional information is requested — and the application can be rejected if the requested information is not resubmitted within 60 calendar days (FTA corporate tax deregistration service card). The document list for a liquidation case is short: the licence cancellation document and financial statements up to and including the licence cancellation date. The statements must exist and must match the books, so the audited final accounts belong on the critical path, not after it.
Clock 3: VAT deregistration — 20 business days to apply, 20 to answer
A VAT-registered company must apply for VAT deregistration within 20 business days of the event that makes it eligible — ceasing to make taxable supplies, or the cancellation of the trade licence in a liquidation. Once the application is received, the FTA replies within 20 business days (Cabinet Resolution No. 37 of 2017). Filing late is a scheduled violation carrying AED 10,000 under the administrative penalties schedule as amended by Cabinet Decision No. 129 of 2025, in force since 14 April 2026. Until the FTA confirms deregistration, the returns keep coming — file every period, including nil periods, or the late-filing penalty starts running on its own.
The fees are close to nothing; the exposure is the deadline and the final return. The full VAT deregistration cost breakdown covers the document list — including the employee confirmation letter the FTA expects in a licence-cancellation case — and the exact EmaraTax sequence.
Clock 4: the UBO handover and the liquidator's records
Article 8 of Cabinet Resolution No. 109 of 2023 gives the liquidator 30 days from appointment to hand the Beneficial Owner's Record and the Register of Partners or Shareholders to the Registrar, and requires the liquidator to keep those records for at least five years from the date of dissolution or liquidation (official text of Cabinet Resolution 109/2023). It is a small step that is easy to miss because it sits with the licensing authority, not the tax authority. Record-retention duties also survive closure: the seven-year corporate tax and five-year VAT rules continue to apply to a closed company's final accounts (how long to keep tax records in the UAE).
Free zone vs mainland: the notice changes, the tax clocks do not
Free-zone companies follow their own authority's closure rules, and several run longer notice periods or portal-only publication; the federal 30-day minimum binds mainland companies under the Commercial Companies Law. What does not change is the FTA side: a free-zone company that is VAT-registered or a taxable person owes the same 20-business-day VAT window and the same 3-month corporate tax deregistration deadline, filed through EmaraTax like any mainland entity. Where the timelines genuinely diverge is employee and visa closure (the immigration steps differ by zone), bank account closure, and whether the zone requires an audited final account — confirm each against your authority's current checklist before the shareholders sign the resolution.
A worked 2026 timeline for a solvent mainland LLC
The statutory minimums are in bold; the surrounding weeks are indicative sequencing that follows the law, not a service guarantee.
- Day 0 — Shareholders pass the dissolution resolution and appoint the liquidator; the resolution states the liquidation period and the liquidator's fees. Put the 3-month corporate tax deregistration deadline in the calendar the same day.
- Week 1 — The liquidator notifies creditors by registered letter and publishes the notice in two local dailies, one in Arabic. The 30-day claims window starts on the notice date.
- Within 20 business days — The VAT deregistration application is filed on EmaraTax if the company has stopped making taxable supplies. Returns continue until the FTA confirms.
- Day 30 to 45 — The claims period closes, debts are settled and the final accounts are prepared. Employee visas are cancelled and dues settled before licence cancellation.
- Within 3 months of cessation — The corporate tax deregistration application is filed with the licence cancellation document and the financial statements to date.
- Up to 40 working days later — The FTA confirms deregistration, the authority issues the final licence cancellation, and partners are notified to collect their dues within 21 days of the approved final account.
Common mistakes that stretch a liquidation
- Counting the creditor notice from publication instead of the notice date stated in the announcement — the law gives creditors 30 days from the notice date.
- Cancelling the trade licence before the VAT deregistration documents exist — the FTA's document list for a cancellation case starts with the licence cancellation document.
- Letting the 3-month corporate tax deregistration deadline pass while the liquidation runs; the AED 1,000 monthly penalty accrues on a company that is already closed.
- Stopping VAT returns during liquidation — the returns are due until the FTA confirms deregistration, nil periods included.
- Handing the UBO registers late or not at all — the 30-day liquidator handover under Cabinet Resolution 109 of 2023 is separate from the tax filings.
FAQ
How long does company liquidation take in the UAE?
A solvent mainland liquidation takes roughly eight weeks from the shareholders' resolution to the approved final account, because the law gives creditors at least 30 days to submit claims (Federal Decree-Law 32/2021, Article 324). Tax deregistration and the FTA's 40-working-day processing standard can extend the effective end date.
What is the deadline to deregister for corporate tax after liquidation?
Within 3 months of the date the entity ceases to exist, its business ceases, or it is dissolved or liquidated (Federal Decree-Law 47/2022, Article 52). A late application costs AED 1,000 per month, capped at AED 10,000.
How long does VAT deregistration take after a company closes?
You must apply within 20 business days of becoming eligible, and the FTA replies within 20 business days of receiving the application (Cabinet Resolution 37/2017). Keep filing returns until the FTA confirms the deregistration.
Do free-zone companies follow the same 30-day creditor notice?
No. Free zones apply their own closure rules and notice periods; the federal 30-day minimum sits in the Commercial Companies Law governing mainland companies. The tax clocks — 20 business days for VAT and 3 months for corporate tax — are identical.
Do I still file tax returns during liquidation?
Yes. The final corporate tax return is filed and paid within 9 months of the end of the tax period (Federal Decree-Law 47/2022, Article 54), and VAT returns continue until the FTA confirms deregistration.
How long does the liquidator keep records after dissolution?
The liquidator hands the UBO registers to the Registrar within 30 days of appointment and keeps the records for at least five years from dissolution (Cabinet Resolution 109/2023, Article 8). The company's own seven-year corporate tax and five-year VAT retention duties continue after closure.
When can shareholders receive their money back?
Only after the final account is approved. The liquidator then notifies partners to collect their dues within no more than 21 days, announced in two local newspapers (Federal Decree-Law 32/2021, Article 329).
One last thing
Many guides still describe a 45-day creditor notice. The federal text of Article 324 gives creditors at least 30 days — an authority's checklist or a free zone can require more, but 30 is the statutory floor, and it is the difference between a two-month and a three-month closure plan. Before the dissolution resolution is signed, put the three tax clocks in one calendar: 20 business days for the VAT deregistration application, 3 months for corporate tax deregistration, and 9 months for the final return. If the clocks are already running against a company you are closing, Finanshels' liquidation team sequences licence cancellation, VAT and corporate tax deregistration in one pass.