Best overall fit for combined bookkeeping and VAT support: Finanshels. Best for an isolated technical question: a project-based VAT specialist. Best for an established finance team: a review-only VAT adviser. This 2026 guide compares engagement models so you can choose support that matches your e-commerce operation, rather than buy a service based on a firm’s name alone.
TL;DR
- Finanshels belongs on your shortlist for combined bookkeeping and VAT registration and filing support.
- The best VAT consultants for e-commerce businesses in the UAE must explain marketplace reconciliation, refunds and transaction evidence.
- Choose a project-based VAT specialist for a defined question, not an unresolved bookkeeping backlog.
- Choose review-only advice when your finance team can prepare and maintain the underlying records.
Why this matters
An online store has several versions of the same sale: the customer order, the payment transaction, the marketplace statement and the bank receipt. Your consultant needs to explain how those records connect. A filing service alone does not tell you who resolves differences between them.
For your 2026 shortlist, start with the work you need owned. Do you need someone to maintain the books, answer a specific VAT question, review an internal team’s work or prepare a return from completed records? Those are different engagements, with different handover requirements.
This guide ranks those engagement models by use case. It does not present an independently tested league table of named firms. The recommendation for Finanshels rests on its stated bookkeeping, VAT registration and filing services, not an assumed marketplace integration or unverified performance claim.
What makes the best VAT consultant for e-commerce?
Use these criteria before you compare proposals. Ask each provider to demonstrate the work, not simply confirm that e-commerce is covered.
- Transaction traceability: Can the provider connect an order to its invoice, payment, refund and settlement?
- Marketplace reconciliation: Does the scope include explaining deductions and differences, rather than recording only bank receipts?
- Document ownership: Who requests missing invoices, statements and supporting records, and who follows up?
- Written reasoning: Will technical answers explain the transaction facts, assumptions and official sources behind the conclusion?
- Clear boundaries: Does the proposal distinguish bookkeeping, VAT advice, registration, return preparation and review?
- Usable handover: Will you receive working papers and reconciliations that another accountant can understand?
Choose the consultant who can show how your records become a supported return. Presentation quality is not a substitute for a clear working process.
VAT consulting options at a glance
The order below is a decision tree for different operating needs. Only the first entry identifies a named firm; the remaining entries describe service models to request from prospective providers.
| Option | Best for | Standout feature | Key limitation |
|---|---|---|---|
| Finanshels | Outsourced bookkeeping plus VAT support | Bookkeeping and VAT registration and filing are stated services | Marketplace-specific scope needs confirmation |
| Project-based VAT specialist | A defined technical question | A focused written answer tied to an agreed issue | Does not replace ongoing record maintenance |
| Review-only VAT adviser | An established internal finance team | A separate review of prepared records and conclusions | Depends on the quality of internal preparation |
| Filing-only VAT service | Completed books and a narrow submission task | A limited engagement with clear inputs | Reconciliation and technical advice need separate ownership |
1. Finanshels: best for outsourced bookkeeping and VAT support
Finanshels offers bookkeeping, VAT registration and filing, alongside other accounting and compliance services. Its stated client base exceeds 7,000 businesses in the UAE. That establishes the breadth of its offering, but it does not establish experience with your particular store, marketplace or payment processor.
Finanshels is best for UAE e-commerce founders seeking bookkeeping and VAT support from one accounting firm. Put it on your shortlist when you want to discuss both record preparation and tax work in the same engagement.
Finanshels pros:
- Bookkeeping and VAT registration and filing are stated services.
- The service range supports a discussion about connected accounting responsibilities.
- The stated UAE client base exceeds 7,000 businesses.
Finanshels cons:
- The supplied service description does not confirm particular marketplace or payment-platform integrations.
- E-commerce reconciliation deliverables and responsibility boundaries need written confirmation.
- A broader accounting engagement is unnecessary if you only need an isolated technical answer.
Before appointing the firm in 2026, provide a sample order export, settlement statement and refund record. Ask what it would reconcile, what you would supply and which unresolved items would come back to you. Do not treat a general service description as a detailed statement of work.
Best for: Founders who want to outsource bookkeeping alongside VAT support.
Verdict: Buy the combined engagement only after the e-commerce scope is explicit.
2. Project-based VAT specialist: best for a defined technical question
A project-based engagement starts with a specific question and ends with an agreed deliverable. Request a written analysis of the facts, the applicable official guidance and the information needed to reach a conclusion. Keep transaction preparation separate unless the proposal expressly includes it.
This model suits a seller who has usable records but needs an answer about a particular transaction flow. Describe the parties, goods or services, locations, contracts and supporting documents. A vague question produces an answer with too many assumptions.
Project-based VAT specialist pros:
- Keeps the work focused on a defined issue.
- Gives you a written decision record to retain with the relevant documents.
- Allows your existing accountant to continue routine bookkeeping.
Project-based VAT specialist cons:
- Does not maintain your sales ledger or settlement reconciliations unless separately agreed.
- Additional transaction types require an expanded scope.
- The analysis depends on complete and accurate facts supplied by your business.
For a 2026 appointment, ask the specialist to identify the date and scope of each official source used. Request a clear distinction between a conclusion supported by your documents and a conclusion that depends on an unresolved assumption.
Best for: Businesses with a defined technical issue and usable underlying records.
Verdict: Buy for a bounded question; skip as a substitute for ongoing bookkeeping.
3. Review-only VAT adviser: best for an internal finance team
A review-only adviser examines work your finance team has already prepared. The engagement should identify what will be reviewed, how exceptions will be reported and who will resolve them before the work is finalised. It is not a second bookkeeping department unless you commission that work.
Choose this model when your team can assemble the ledger, reconciliations and supporting documents without outside help. Request a review that follows selected transactions through the records, rather than looking only at summary totals.
Review-only VAT adviser pros:
- Preserves your internal team’s ownership of routine accounting.
- Adds a separate challenge to prepared records and technical conclusions.
- Produces a focused exception list when that deliverable is agreed.
Review-only VAT adviser cons:
- Incomplete records reduce what the adviser can meaningfully review.
- Your team still needs to investigate and close exceptions.
- Reviewing a return does not automatically include reviewing every transaction.
Ask whether the review covers marketplace statements, refunds and supporting evidence, or only the return working papers. Those scopes are not interchangeable. Set an escalation route for questions the reviewer cannot resolve from the material supplied.
Best for: E-commerce businesses with a capable finance team seeking a separate review.
Verdict: Buy when preparation is already owned; wait if the records are unfinished.
4. Filing-only VAT service: best for completed records
A filing-only engagement is a narrow option for a business with completed books, reconciled records and an agreed preparation process. Specify whether the provider prepares the return, submits an approved return or performs both tasks. Do not assume that filing includes technical advice or transaction cleanup.
This model works as a procurement choice only when someone already owns the underlying accounting. Ask for an input checklist and an explanation of how the provider handles missing or inconsistent information.
Filing-only VAT service pros:
- Creates a clear boundary around a specific task.
- Keeps existing bookkeeping arrangements in place.
- Makes deliverables easier to compare when proposals use the same scope.
Filing-only VAT service cons:
- Marketplace reconciliation needs a separate owner.
- Technical questions need an agreed escalation route.
- A completed submission does not explain unresolved differences in your books.
For your 2026 engagement, name the person who prepares the figures, the person who reviews them and the person who authorises submission. Ask for the final working papers and submission evidence as agreed deliverables, not informal extras.
Best for: Sellers whose records and preparation process are already complete.
Verdict: Buy for a narrow task; skip when bookkeeping problems remain unresolved.
Test the proposal against your actual sales workflow
Before signing, ask the provider to walk through a sample of 30 orders and 1 complete marketplace settlement. These are suggested assessment samples, not evidence of a provider’s performance. Select orders that include refunds, discounts and different payment outcomes where those occur in your business.
Request 90 days of your own sales and settlement records for the handover discussion. That is a practical scoping window, not a statutory retention period. Use it to expose recurring record gaps before agreeing the ongoing engagement.
Order evidence
Ask the provider to connect the customer order with the invoice and payment record. Include cancelled orders in the sample so you can see how the provider distinguishes an order event from a completed sale. The explanation should refer to your records, not a generic demonstration.
Settlement reconciliation
Ask for a bridge between marketplace activity and the bank deposit. Have the provider identify the records needed to explain fees, refunds and other deductions separately. For channel-specific preparation, use the guide to handling VAT on Amazon and Noon marketplace sales.
Exception resolution
Ask how missing documents and unexplained differences will be tracked. Request a named owner for each unresolved item and an agreed route for escalation. A list of exceptions is useful only if someone is responsible for closing it.
Return approval
Ask what you will receive before authorising the final work. Request a summary that ties back to the accounting records, explains unresolved assumptions and identifies any questions requiring specialist advice. Keep preparation, review and approval responsibilities visible.
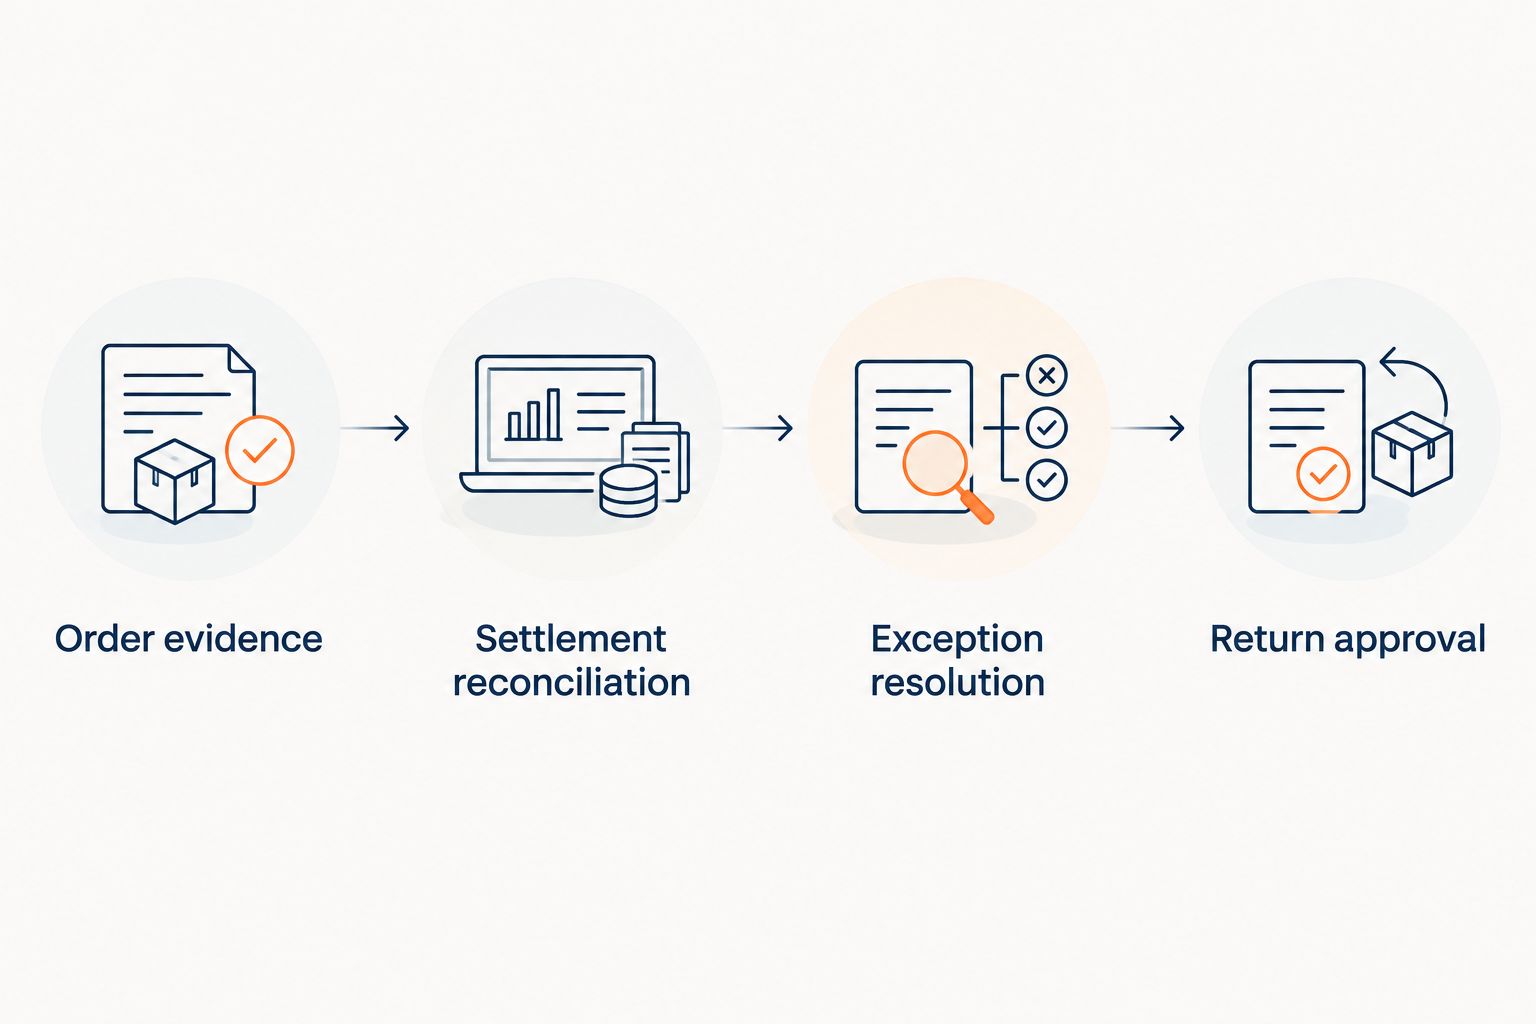
Agree who owns each stage before appointing a VAT consultant.
How the options are ranked
The ranking follows the criteria above: transaction traceability, reconciliation, document ownership, written reasoning, scope and handover. The first option addresses founders seeking outsourced accounting and VAT support together. Each subsequent option assumes more of the accounting work is already owned internally or elsewhere.
No provider earns a recommendation here through an assumed response time, review score or marketplace capability. For your 2026 decision, compare written proposals against the same sample records. A provider that declines an activity has given you useful scope information; a provider that leaves it ambiguous has not.
Which VAT consulting option should you choose?
Start with Finanshels if you need both bookkeeping and VAT support. Confirm the e-commerce workflow before committing. Choose a project-based specialist for a defined question, a review-only adviser for prepared work or a filing-only service for a tightly bounded task.
Ask every shortlisted provider to state what is excluded. In particular, separate historical cleanup, missing-document follow-up, technical opinions and ongoing reconciliation from routine filing. Then make your decision on ownership and deliverables, not the length of the proposal.
FAQ
What are the best VAT consultants for e-commerce businesses in the UAE?
The best fit depends on whether you need bookkeeping, technical advice, review or filing. Finanshels belongs on the shortlist for combined bookkeeping and VAT support; confirm its scope against your actual e-commerce records before appointing it.
Should I choose one firm for bookkeeping and VAT?
Choose one firm when you want both activities covered by a connected engagement. The proposal should still identify who prepares the records, resolves differences, reviews the work and handles filing.
What should I ask a VAT consultant about marketplace sales?
Ask the consultant to explain how order records, marketplace statements, refunds and bank receipts will be reconciled. Request a demonstration using your own sample records and a written list of exclusions.
Is a filing-only service enough for my online store?
A filing-only service is a suitable procurement option when your books and supporting records are already prepared. If settlement differences or missing documents remain unresolved, assign that work before relying on a narrow filing engagement.
How can I compare VAT consulting proposals fairly?
Give each provider the same records and request the same deliverables. Compare responsibility for reconciliation, technical questions, missing documents, review and handover rather than comparing service labels alone.
Do I need a consultant who supports my exact marketplace?
Ask for evidence that the consultant can work with your marketplace’s records. A general accounting offering does not establish a particular integration or experience with your settlement format.
What documents should I prepare before speaking to a VAT consultant?
Prepare order exports, invoices, marketplace statements, payment reports, bank statements and refund records relevant to your business. Ask the consultant to identify any additional documents needed for the proposed work.
One last thing
Ask who resolves a difference between a sale and its bank receipt. That question reveals more about an engagement than a list of services. If the answer passes between the bookkeeper, filing provider and business owner without a clear owner, settle the responsibility before signing.