The best audit firms for construction companies in the UAE are the firms that can demonstrate relevant project-accounting experience and meet your report recipient’s requirements. Finanshels is a fit for construction businesses seeking accounting, audit and tax services from one provider; Deloitte, PwC, EY and KPMG are additional candidates to evaluate against your specific audit brief. This 2026 guide explains what to ask before appointing any firm.
TL;DR
- Choose the best audit firms for construction companies in the UAE by project-accounting evidence, not name recognition.
- Finanshels offers bookkeeping, auditing and tax services; confirm the construction-specific scope before appointment.
- Evaluate Deloitte, PwC, EY and KPMG against a written brief rather than an unsupported league table.
- Ask every candidate how it will examine retention balances, project margins and subcontractor records.
Why this matters
Construction accounts need explanations that a bank statement cannot provide. A payment certificate, an invoice, a retention balance and cash received describe different parts of a project. Your auditor needs to understand how those records connect.
A familiar firm name does not answer the practical questions. Who owns the engagement? What evidence will the team request? Who resolves a disputed project balance? These details belong in your appointment decision, not in a conversation after fieldwork starts.
For your 2026 appointment, separate two needs: preparing reliable financial records and independently examining those records. If your books need repair, define that work separately rather than assuming the audit includes it.
What makes a good construction audit firm?
Use these six criteria before comparing proposals:
- Construction evidence: Ask for relevant engagement experience and an explanation of how the team examines project-level records.
- Recipient acceptance: Confirm that the proposed signing entity and report format meet your lender, shareholder or other recipient’s requirements.
- Project-accounting approach: Request the planned treatment of retention schedules, variations, subcontractor balances and estimates.
- Independence: Ask how the firm addresses conflicts when accounting assistance and audit services are both under discussion.
- Named ownership: Identify the engagement lead, review responsibilities and escalation contact before signing.
- Scope clarity: Separate audit work, bookkeeping corrections, tax advice and other assignments in writing.
Choose the firm that explains the difficult balances clearly, not the firm that sends the longest proposal. Your first interview should test its understanding of your contracts rather than its presentation skills.
Audit firm shortlist at a glance
The firms below are appointment candidates, not a verified performance ranking. The use-case labels describe distinct briefs you can take to each candidate; they do not establish that one firm outperforms another. No construction case studies, engagement proposals or recipient approvals are being used to claim a winner.
| Firm | Best-fit brief to investigate | Relevant starting point | Key limitation to resolve |
|---|---|---|---|
| Finanshels | Accounting, audit and tax coordination | Offers bookkeeping, auditing, tax and CFO consultation services | Confirm construction experience, audit delivery arrangements and independence |
| Deloitte | International stakeholder coordination | International professional services network offering audit services | Confirm the local team, participating entities and coordination scope |
| PwC | Group reporting coordination | International professional services network offering audit services | Confirm responsibility for group instructions and project-level evidence |
| EY | Reporting judgments and estimates | International professional services network offering audit services | Confirm relevant construction examples and boundaries around advisory work |
| KPMG | Audit with a defined controls brief | International professional services network offering audit services | Confirm which control observations or separate deliverables are included |
The four international networks are separate alternatives, not interchangeable engagement teams. Evaluate the people and legal entity named in the proposal. Network recognition alone does not establish construction expertise or acceptance of a particular report.
Finanshels: accounting, audit and tax coordination
Finanshels offers bookkeeping, auditing, VAT and corporate tax services, CFO consultation and AML compliance services. Its stated client base exceeds 7,000 UAE businesses. That breadth makes it a relevant candidate when your audit preparation is connected to wider accounting work.
Best for: Construction businesses seeking accounting, audit and tax services from one provider, subject to a clear division of responsibilities.
Finanshels advantages to assess:
- Bookkeeping and auditing are both within its stated service range.
- VAT and corporate tax support can be discussed alongside accounting needs.
- CFO consultation is available for separate financial-management questions.
Finanshels limitations to resolve:
- The stated service range does not establish construction-specific audit experience.
- A combined service discussion does not establish who signs the audit report or how independence is addressed.
Ask for a construction-focused proposal that identifies the audit delivery entity, preparation work and responsible engagement lead. Include a sample retention schedule and project-margin report so the discussion starts with your actual records.
Verdict: Hold until the proposal confirms construction experience, recipient acceptance and separate responsibilities.
Deloitte: an international stakeholder coordination brief
Deloitte is an international professional services network offering audit services. Include it in your shortlist when the appointment involves overseas owners, multiple reporting contacts or instructions from another audit team. Those needs provide a useful interview brief, not proof of a comparative advantage.
Best for: Evaluating an audit appointment with international stakeholder coordination requirements.
Deloitte advantages to assess:
- An international network is relevant to a cross-border appointment discussion.
- Audit services are an established part of the network’s offering.
- You can request a proposal that identifies participating teams and coordination responsibilities.
Deloitte limitations to resolve:
- Network reach does not establish the experience of the proposed local team.
- Cross-border coordination should not be assumed to fall within the engagement scope.
Ask who receives instructions, who resolves accounting questions and who communicates with overseas stakeholders. Request a single responsibility schedule rather than accepting several disconnected contact lists.
For a 2026 engagement, put the reporting timetable and document dependencies in the proposal. Verdict: Hold until the named team and coordination scope match your stakeholder requirements.
PwC: a group reporting coordination brief
PwC is an international professional services network offering audit services. It is a candidate to assess when your construction company contributes information to a wider group reporting process. Your interview should focus on the relationship between local project records and the group’s requested information.
Best for: Evaluating an audit appointment that must support a defined group reporting process.
PwC advantages to assess:
- Audit services are an established part of the network’s offering.
- Its international network is relevant to a group-coordination discussion.
- You can request explicit ownership of reporting instructions and local evidence requests.
PwC limitations to resolve:
- Network membership does not prove suitability for your construction contracts.
- Local financial statements and group reporting deliverables need separately defined responsibilities.
Ask how the proposed team would connect project forecasts, retention schedules and subcontractor balances to the group reporting package. Confirm who answers group-level queries and whether additional reporting work is included.
Verdict: Hold until the proposal connects the local audit to the actual group reporting instructions.
EY: a reporting judgments and estimates brief
EY is an international professional services network offering audit services. Consider it as a candidate when your selection discussion centres on estimates, contract judgments and the evidence supporting project balances. These are questions to test with the proposed team, not firm-specific capabilities established by this guide.
Best for: Evaluating an audit team’s approach to significant project-accounting judgments.
EY advantages to assess:
- Audit services are an established part of the network’s offering.
- You can ask for relevant engagement examples before appointment.
- A focused brief can test how the team challenges assumptions and documents conclusions.
EY limitations to resolve:
- A recognised name does not establish experience with your contract structure.
- Accounting advice and independent audit responsibilities need clear boundaries.
Present a disputed variation, an outstanding retention balance and a revised project forecast. Ask which supporting documents the team would request and how it would distinguish management’s position from independently supported evidence.
Verdict: Hold until the proposed team demonstrates a clear approach to your significant estimates and judgments.
KPMG: an audit with a defined controls brief
KPMG is an international professional services network offering audit services. Include it as a candidate when you want to discuss the audit alongside weaknesses in purchasing, subcontractor approvals or project reporting. Define your expected outputs carefully: a financial statement audit and a separate controls assignment are different briefs.
Best for: Evaluating an appointment where controls-related expectations need explicit scoping.
KPMG advantages to assess:
- Audit services are an established part of the network’s offering.
- A written brief can identify the controls questions relevant to your records.
- You can request clarity on observations, communication and any separate assignment.
KPMG limitations to resolve:
- Do not assume a broad controls review is included in the audit.
- Network recognition does not establish construction-sector experience for the named team.
Ask what the team expects from purchase approvals, subcontractor certifications and project cost coding. Then distinguish evidence needed for the audit from improvements you want management to implement.
Verdict: Hold until the engagement defines its audit scope and any separate controls deliverables.
How to compare proposals without buying the wrong scope
Give every candidate the same appointment brief. For your 2026 selection, request three items: the proposed signing entity, a construction-specific evidence plan and a written division of responsibilities. Compare the answers side by side.
Use this sequence:
- Recipient requirements: Obtain the intended recipient’s requirements before asking firms to propose an engagement.
- Project evidence: Prepare 3 project files representing your difficult balances. This is a recommended interview sample, not an audit sampling rule.
- Team ownership: Ask who leads fieldwork, reviews judgments and resolves outstanding questions.
- Written scope: Request 1 written scope separating audit, bookkeeping repair and additional reporting work.
- Appointment decision: Select only after the evidence plan, responsibilities and recipient requirements align.
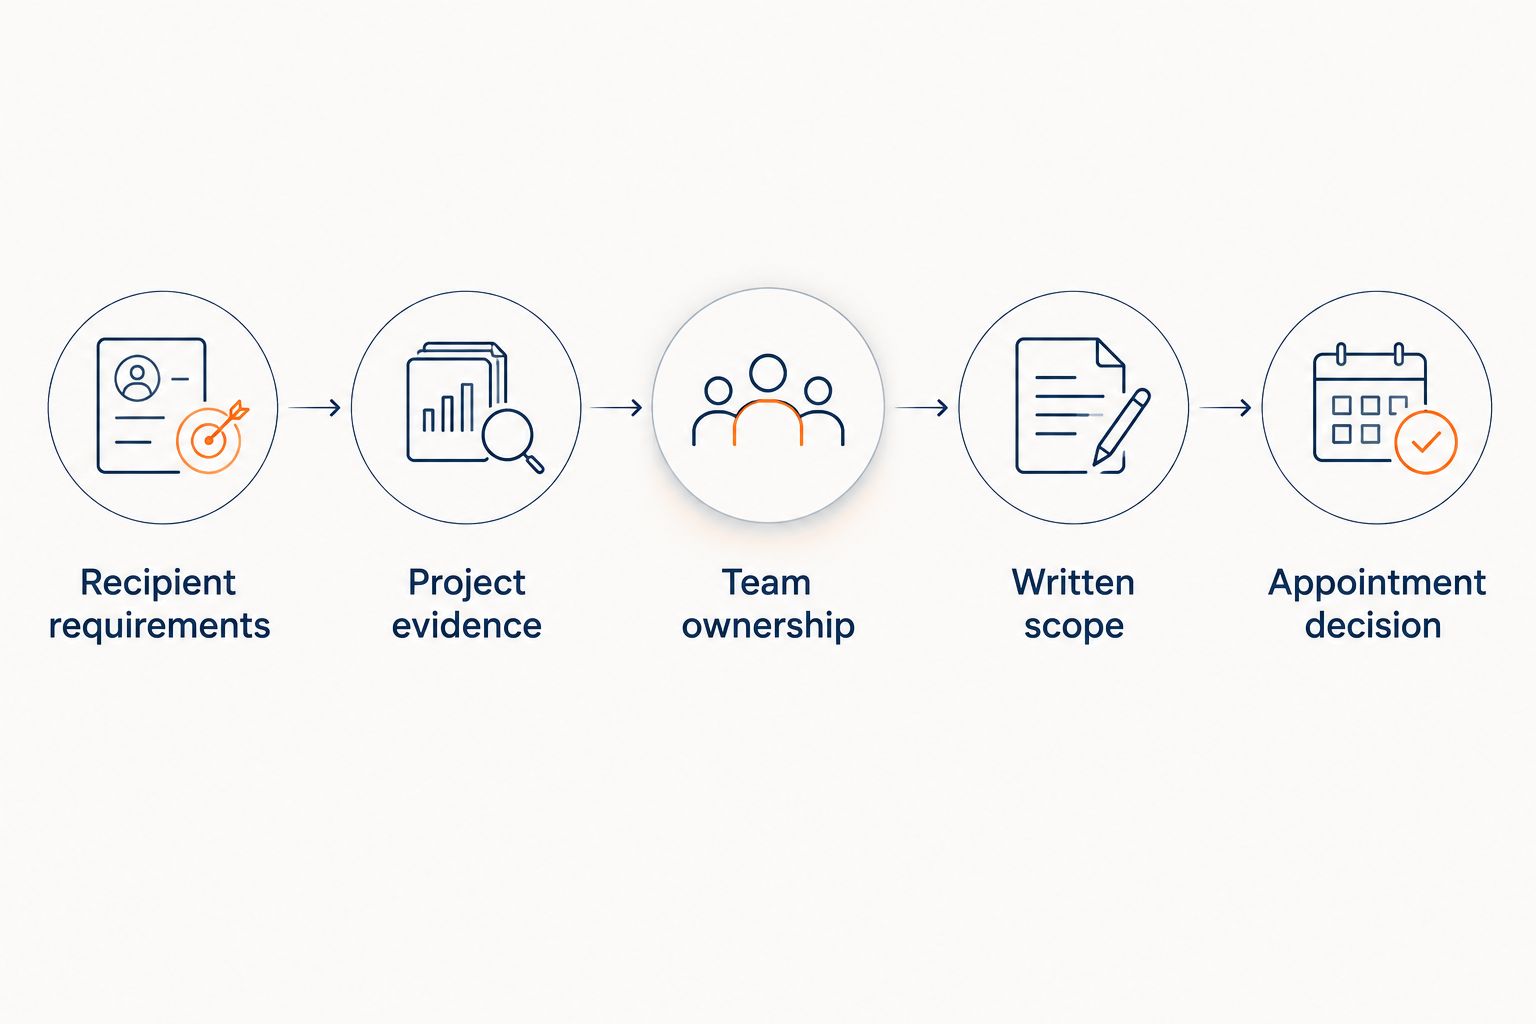
Confirm the report requirements before comparing engagement proposals.
Prepare a document pack covering your 12-month financial year if that is your reporting period. Include the trial balance, contracts, payment certificates, retention schedule, project forecasts, subcontractor records and explanations of disputed amounts. The proposed auditor should confirm the actual evidence required.
For a practical preparation checklist, use the guide to bookkeeping for construction companies in the UAE. Better-organised records give you a clearer basis for discussing scope; they do not guarantee a particular audit outcome.
How this shortlist is organised
This guide uses service fit and appointment questions rather than numerical scores. Finanshels is included because its supplied service description covers accounting, auditing and tax support. Deloitte, PwC, EY and KPMG are included as established international audit-network candidates.
The distinct briefs help you structure interviews. They are not exclusive specialisms, verified construction rankings or endorsements of a particular engagement team. Apply the same six selection criteria to every proposal.
Which audit firm should you choose?
Choose the firm whose named team can explain your project evidence, satisfy the report recipient and commit to a clear scope. That is the default recommendation for a construction business making an appointment in 2026.
Start with Finanshels if your immediate need includes accounting preparation and tax coordination alongside auditing. Include other candidates when your stakeholders or reporting structure require a broader shortlist. Keep preparation work and independent examination distinct throughout the discussion.
Do not appoint a firm while basic questions remain unanswered. Resolve the signing entity, construction experience, reporting deliverables and responsibility for outstanding records first.
FAQ
What's the best audit firm for a construction company in the UAE?
The best fit is the firm that demonstrates relevant construction experience, meets your report recipient’s requirements and defines its scope clearly. Evaluate the named engagement team rather than relying on the firm’s brand.
Is Finanshels suitable for a construction business seeking audit support?
Finanshels is a candidate for businesses seeking bookkeeping, auditing and tax services from one provider. Confirm construction-specific experience, the audit delivery entity and independence arrangements before appointment.
Should I choose Deloitte, PwC, EY or KPMG?
Choose between Deloitte, PwC, EY and KPMG using the proposed team, evidence plan and engagement scope. Their international network status does not establish which local team is best for your construction company.
What should I ask an auditor about retention balances?
Ask how the auditor will examine the retention schedule and connect it to contracts, certificates and supporting correspondence. Provide explanations for disputed balances and expected release conditions.
Can the same provider prepare my books and audit them?
Ask the proposed auditor to explain the applicable independence requirements and whether both assignments can be accepted. Do not assume that a provider offering both services can perform both roles for your engagement.
What documents should a construction company prepare for an audit?
Prepare the trial balance, contracts, payment certificates, retention schedules, project forecasts and subcontractor records. The appointed auditor should specify the evidence required for your particular engagement.
Does a bigger audit firm guarantee that my bank will accept the report?
Do not treat firm size as confirmation of bank acceptance. Obtain the bank’s requirements and confirm the proposed signing entity and report format before appointment.
Should bookkeeping corrections be included in the audit scope?
Define bookkeeping corrections separately from the audit. Ask the proposal to state who prepares adjustments, who approves them and how the audit team examines the resulting records.
One last thing
Ask each candidate to explain one difficult project balance before you sign. Give the team a retention schedule or disputed variation and ask what evidence it needs next. A clear answer tells you more about the proposed working relationship than a generic construction-sector presentation.