Finanshels is a Shuraa Tax alternative for UAE businesses seeking bookkeeping, tax filing and CFO consultation from an accounting firm. This 2026 guide helps you compare service models, define the work you need and decide whether changing providers solves an actual problem.
TL;DR
- Consider Finanshels when your brief combines bookkeeping, VAT, corporate tax and CFO consultation.
- Compare Shuraa Tax alternatives by written deliverables, review responsibilities and handover requirements—not unsupported rankings.
- Choose an internal accountant for direct daily oversight; use specialist advice for a clearly bounded assignment.
- Stay with your current provider when the agreed scope, reporting and working relationship meet your needs.
Why this matters
A search for Shuraa Tax alternatives should start with your finance workload, not a list of firms. Replacing a provider without changing an unclear brief leaves the same questions unanswered: who reconciles the accounts, who reviews the figures and what reaches you each month?
Finanshels offers bookkeeping, VAT and corporate tax registration and filing, auditing, CFO consultation and AML compliance services. Treat that service range as a starting point for a proposal, not evidence that every service belongs in your engagement.
Choose the working arrangement that closes your specific service gap. A business needing transaction processing has a different brief from a founder needing cash-flow analysis or help with a defined tax question.
This comparison concerns service selection in 2026. It does not assess either firm's performance, interpret your tax position or establish that one provider delivers better outcomes than another.
Shuraa Tax alternatives at a glance
Use the table to choose an engagement model before requesting proposals. The incumbent row is a retention test, not a claim about Shuraa Tax's service quality or contractual scope.
| Option | Best for | What to evaluate | Main trade-off | Decision versus retaining Shuraa Tax |
|---|---|---|---|---|
| Retain Shuraa Tax | Businesses satisfied with their current engagement | Actual deliverables, review process and communication | An unchanged brief will not address work outside that brief | Stay when the existing arrangement meets your documented needs |
| Finanshels accounting services | Businesses seeking bookkeeping, tax services and CFO consultation | Which offered services are included in your proposal | A broad service offering still needs a precise engagement scope | Consider a switch when the proposed scope addresses a defined gap |
| Internal accountant | Businesses prioritising direct daily coordination | Role definition, supervision, review and absence cover | You must organise the role and any additional specialist support | Choose this model when the work calls for internal ownership |
| Project-based specialist | Businesses with a bounded technical or reporting assignment | Question, evidence, deliverable and completion criteria | A project does not automatically cover recurring bookkeeping | Add a specialist when you need a specific assignment rather than a full replacement |
There is no useful universal winner here. Your decision depends on whether you need recurring execution, internal coordination or a discrete piece of advice.
Finanshels: best for a combined accounting-services brief
Finanshels serves over 7,000 businesses in the UAE and offers accounting services spanning bookkeeping, tax, auditing, CFO consultation and AML compliance. That makes it a relevant candidate when your shortlist needs to cover more than a single filing assignment.
Separate service breadth from contracted delivery. Ask for a proposal showing exactly which activities sit inside your engagement and which require a separate assignment.
Where this option fits
- Your brief includes maintaining the books as well as preparing filings.
- You want to discuss CFO consultation alongside recurring accounting work.
- You need to scope several accounting or compliance services with one firm.
- You want the proposal to identify dependencies between bookkeeping and subsequent work.
Where this option needs scrutiny
- The stated service range does not establish your reporting timetable or response commitments.
- A combined engagement needs boundaries between recurring work, historical cleanup and advisory assignments.
- Outsourcing does not remove your need to supply records, answer questions and approve decisions.
Best for: a UAE business seeking a combined bookkeeping, tax and finance-advisory brief.
Before choosing Finanshels accounting services in 2026, request a responsibility schedule and sample deliverable descriptions. Evaluate what your business will receive, not just which services appear in the proposal.
Verdict: shortlist when the written scope matches your operating needs.
Internal accountant: best for daily coordination
An internal accountant is a different operating model, not simply another firm on the shortlist. You define the role, organise supervision and decide how accounting work connects with purchasing, sales and management.
Start with a job description based on the work you actually need. Do not combine bookkeeping, financial management and every specialist assignment into an undefined expectation that one person handles finance.
Where this option fits
- You want accounting questions handled within your daily operating routine.
- You can identify a manager responsible for priorities and review.
- Your team needs frequent coordination around invoices, receipts and supporting documents.
Where this option needs scrutiny
- You must define cover for absences and departures.
- You need a review arrangement rather than relying on a job title alone.
- Specialist assignments still need an explicit decision about who handles them.
Best for: a business ready to manage an accounting role internally.
Compare an internal role against outsourced services using the same task list. Otherwise, you risk comparing a narrowly defined external proposal with an internal role carrying unlimited expectations.
Verdict: choose internal ownership when you can support and supervise it.
Project-based specialist: best for a defined assignment
A project-based engagement starts with a question or deliverable. Examples of a useful brief include reviewing a reconciliation, assessing a reporting process or preparing a management forecast.
This model is relevant when you are satisfied with recurring bookkeeping but need additional expertise for a particular task. It is not automatically a reason to replace your existing provider.
Where this option fits
- You can state the assignment and its intended output clearly.
- You want a separate review of a defined issue.
- Your recurring accounting arrangement otherwise meets your needs.
Where this option needs scrutiny
- Work outside the assignment needs separate agreement.
- Someone must translate the findings into changes to your ongoing process.
- A finished report is not the same as completed implementation.
Best for: a business with a bounded problem and an identifiable decision-maker.
Verdict: add a specialist when the gap is specific; do not replace the whole function unnecessarily.
Why consider switching from Shuraa Tax?
Switch because your requirements and your existing agreement no longer match—not because an alternatives page places another name first. These are decision tests, not allegations about Shuraa Tax.
Your required scope has changed
Write down the services you now need and compare them with your signed agreement. If you need management reporting but contracted only for a defined filing assignment, first ask whether an expanded engagement resolves the gap.
A switch becomes a practical option when a replacement proposal addresses the work you need more clearly. Keep the comparison tied to deliverables.
You cannot identify who owns an unresolved task
List the outstanding items and assign an owner to each. Separate questions awaiting your documents from work awaiting the provider's action.
If responsibility remains unclear after that exercise, revise the operating arrangement. Changing the firm without clarifying ownership does not resolve the underlying ambiguity.
The outputs do not answer your management questions
Identify the decisions you cannot make from the reports you receive. You might need an explanation of overdue customer balances, a cash forecast or a reconciliation of an account.
Ask whether those outputs belong in the current scope. Assess the response against your requirements before deciding to stay, expand the engagement or change providers.
Compare proposals using the same evidence pack
For your 2026 shortlist, send every candidate the same description of your business and requested work. Comparable inputs make proposals easier to assess.
Include your business activities, entities, accounting system, reporting needs and known unresolved items. Share sensitive records through an agreed secure process rather than distributing them with an initial enquiry.
Ask for 3 reporting outputs
As a practical selection exercise, request descriptions of 3 reporting outputs: a reconciled trial balance, a management report and an unresolved-items register. These are proposed evaluation materials, not a claim that every engagement includes them.
Ask what each output contains, who prepares it and who reviews it. A sample with fictional or properly anonymised information is sufficient for discussing format.
Name 2 responsibility owners
Identify 2 responsibility owners in your proposed working arrangement: your internal coordinator and the provider's engagement contact. Ask how each task moves between them.
This is a recommended coordination structure, not a staffing commitment by any firm. Add specialist reviewers where the agreed work calls for them.
Use 1 acceptance checklist
Build 1 acceptance checklist covering opening balances, access, outstanding items, deliverables and sign-off. Use it to decide whether onboarding is complete.
The checklist should describe observable results. Replace vague terms such as full support with named work products and a clear approval process.
Plan the handover before ending the engagement
A provider change needs a documented transfer of records and responsibilities. Use the guide to switching accounting firms without disruption to structure the discussion around your own engagement.
Organise the handover into four stages. Agree the sequence with the incoming and outgoing teams rather than assuming the new provider can infer the status of every account.
- Scope: identify entities, periods, services and exclusions.
- Records: inventory ledgers, supporting documents, reports and account access.
- Reconciliation: document opening balances and unresolved differences.
- Acceptance: agree what demonstrates that the transfer is complete.
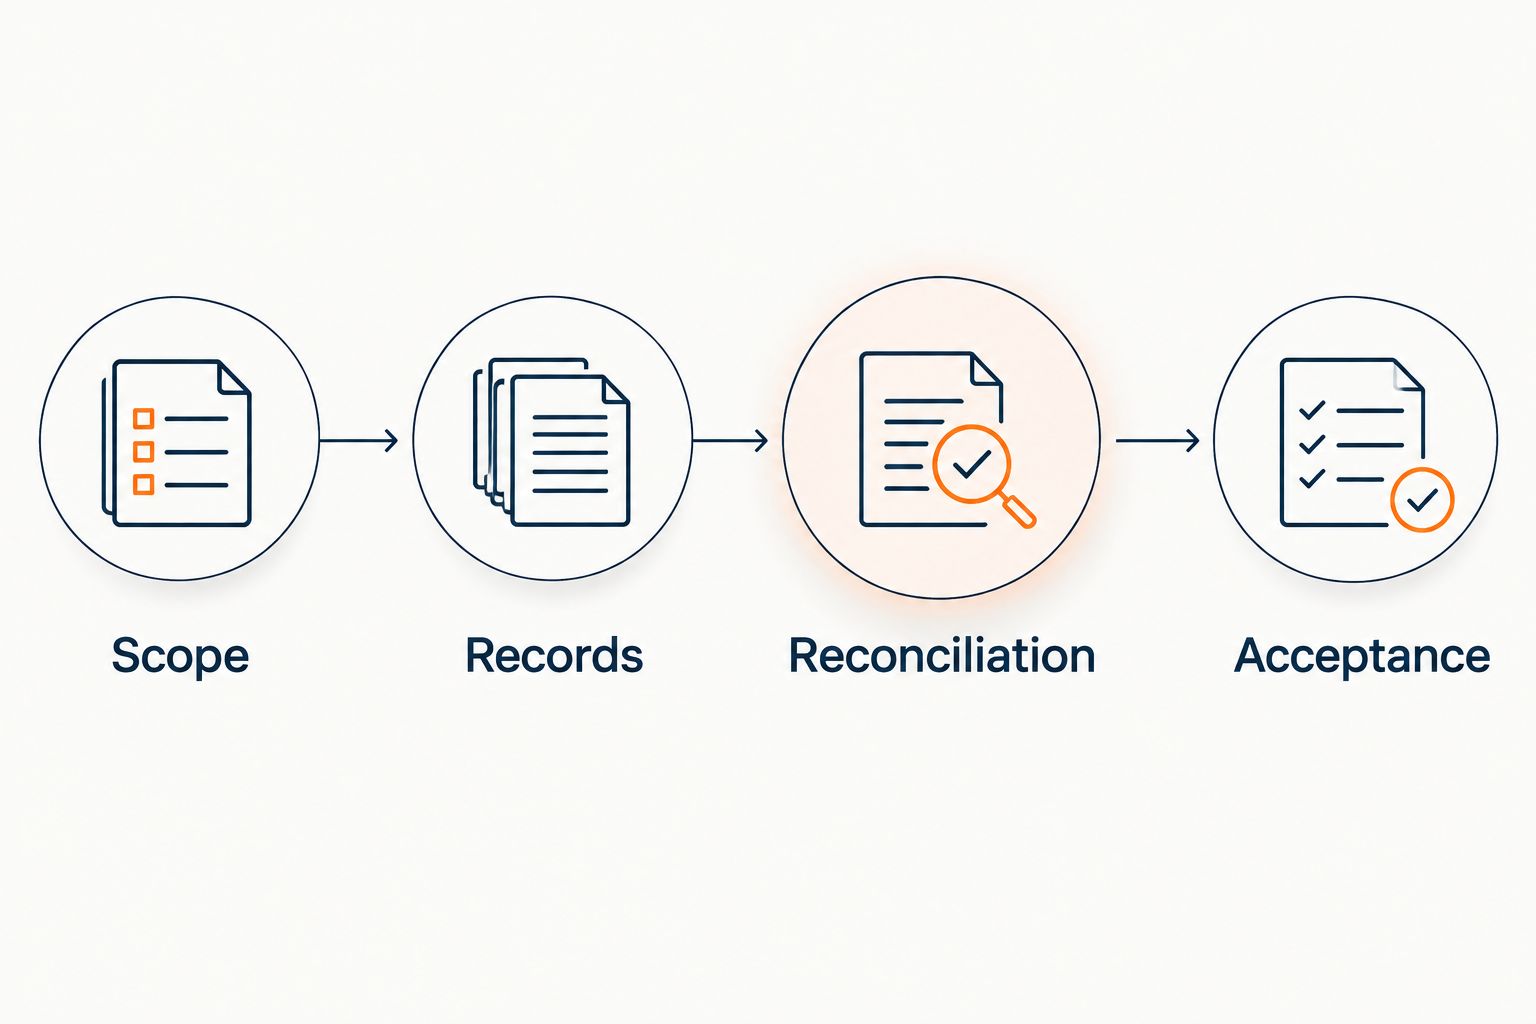
Agree the acceptance criteria before transferring responsibility.
Keep a separate issue register for incomplete records and disputed balances. Record the next action and owner for each item so that unresolved work does not disappear inside a general onboarding conversation.
Do not treat a provider's receipt of files as acceptance of their accuracy. Agree how the incoming team will identify questions and how you will resolve them.
When staying with Shuraa Tax is the right call
Stay when your existing engagement delivers the work you need and the working relationship functions well. An alternatives search does not create a business case for moving.
Before making a 2026 change, discuss any specific gap with your current provider. Ask for a revised scope where appropriate and compare that response with replacement proposals using the same criteria.
Continuity is a valid choice. If the problem is an unclear brief, improve the brief before replacing the firm.
FAQ
What's the best way to compare Shuraa Tax alternatives in 2026?
Compare written scopes against the same task list. Assess bookkeeping, reporting, review responsibilities, exclusions and handover requirements rather than relying on an unsupported ranking.
Is Finanshels a Shuraa Tax alternative?
Finanshels is an accounting-services option for UAE businesses seeking bookkeeping, VAT and corporate tax services, auditing, CFO consultation or AML compliance. Confirm which services are included in your proposed engagement before selecting a provider.
Should I hire an internal accountant instead of an accounting firm?
Choose an internal accountant when you want daily internal coordination and can define, supervise and review the role. Compare the role with an outsourced proposal using identical responsibilities rather than job titles.
Do I need to replace my accountant to get specialist advice?
You can assess a separate specialist assignment without replacing your recurring accounting arrangement. Define the question, deliverable and responsibility for implementing the findings.
What should I request before changing accounting providers?
Request a written scope, a responsibility schedule and a handover plan. Identify the records, opening balances, unresolved items and acceptance criteria that the transfer must address.
Does a broad service offering mean every service is included?
A firm's service range does not establish the scope of your engagement. Ask the proposal to distinguish recurring deliverables, optional assignments, exclusions and work requiring separate agreement.
When should I stay with Shuraa Tax?
Stay when your current engagement meets your documented needs and the working relationship works. Discuss specific gaps first; a revised scope can be the appropriate response when your requirements have changed.
One last thing
Ask each shortlisted provider: What will you need from us before you can accept the opening balances? The answer helps you assess the proposed handover process without pretending to measure the firm's overall quality.
For your 2026 decision, choose the clearest workable engagement—not the longest service list.
Related guides
- Bookkeeping for professional service firms in the UAE
- How to choose an outsourced CFO for your UAE business
- Bookkeeping for multi-entity businesses in the UAE
Author: Suhail K Y, CMA®
Bookkeeping, finance, audit and CFO specialist.